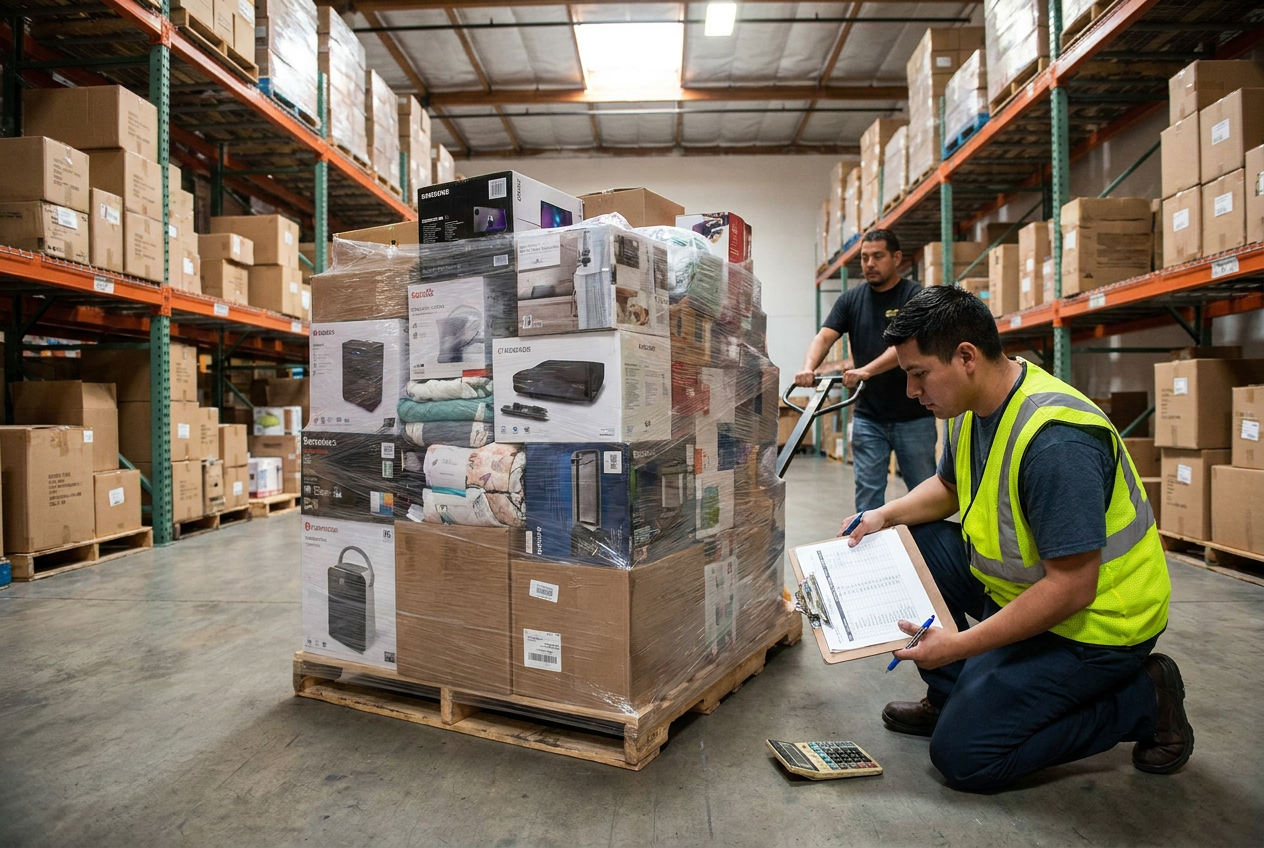
A mixed liquidation pallet arrives with one purchase price, but its contents may include appliances, clothing, incomplete tools, and unsellable pieces. Assigning the same cost to every item is simple; deciding whether that assignment meaningfully represents the inventory takes more work.
Liquidation inventory cost allocation is the process of distributing a bulk acquisition cost across the items or groups purchased. A defensible method reconciles to the amount actually incurred, uses a documented allocation basis, and keeps acquisition cost separate from expected selling price. Manifest retail figures alone cannot establish what customer returns, shelf pulls, or salvage will sell for.
This guide compares practical approaches for independent resellers buying from PalletCove Liquidation, a wholesale liquidation supplier in Dallas, Texas. The examples are hypothetical bookkeeping illustrations, not inventory offers, resale forecasts, or tax advice.
What belongs in the inventory cost pool?
The cost pool is the amount you intend to assign to a particular lot. Start with the invoice and payment records, then identify any additional acquisition-related costs your accounting policy requires you to capitalize. Applicable rules depend on your accounting framework, tax method, and circumstances; confirm the treatment with your accountant.
At PalletCove, freight is included in the listed price. Free shipping is the only delivery option on every order to all 48 contiguous states. Do not add a second estimated inbound shipping amount to the invoice cost: that would count the same acquisition component twice.
PalletCove covers sales tax on qualifying orders. Do not add a hypothetical tax amount that you did not incur. Separately incurred receiving, testing, or preparation costs need individual review rather than automatic inclusion.
Keep three figures distinct:
- Allocated acquisition cost: the portion of the cost pool assigned to an item or group.
- Expected selling price: an estimate supported by relevant market evidence, not a promise.
- Net proceeds: actual sale receipts less applicable selling costs.
Inventory allocation also differs from subsequent write-downs and from cost-flow assumptions such as FIFO or weighted average. Our liquidation overview provides broader buying context, but accounting decisions should follow a consistent, professionally reviewed policy.
Allocate the cost you actually incurred; do not turn a manifest’s retail column into an assumed resale value.
Match the method to the load and its condition
A manifested lot supplies an item-level or grouped list, which may include descriptions, quantities, identifiers, condition labels, and reference retail amounts. A category-level lot describes the merchandise mix more broadly. Neither format removes the need to reconcile the goods received.
A liquidation pallet can contain highly unlike items. A truckload or full trailer can multiply those differences across numerous pallets. LTL describes less-than-truckload transportation, not the quality, count accuracy, or value of the merchandise. See the pallet and load types guide when comparing formats.
Condition grade labels require their own definitions:
- Overstock: generally excess inventory; inspect packaging, age, and completeness rather than assuming perfection.
- Shelf pulls: merchandise removed from selling displays or shelves, potentially with handling or packaging wear.
- Customer returns: merchandise returned by customers, with potentially varied functionality and completeness.
- Salvage: inventory intended for recovery, repair, parts, or another limited disposition, depending on the listing.
There is no universal grading standard across liquidation suppliers. Record the listing’s definition separately from your own inspection findings. All PalletCove merchandise is sold as-is for resale; a grade is not a guarantee of each item’s condition.
Compare the breadth of general merchandise liquidation with the scale of liquidation truckloads. The Amazon General Merchandise Truckload listing and Shoes Truckload listing illustrate different assortment types; consult current listings for their actual descriptions and terms.
PalletCove is an independent reseller and is not affiliated with, endorsed by, or sponsored by any retailer named.
Compare documented allocation methods
The following approaches are working allocation techniques, not blanket statements about acceptable tax reporting. Choose a basis that reasonably reflects the lot, document its limitations, and have your accountant approve material reporting decisions.
| Method | Allocation basis | Useful when | Main limitation |
|---|---|---|---|
| --- | --- | --- | --- |
| Equal cost per unit | Verified quantity | Units are economically similar | Distorts costs across unlike items |
| Relative estimated selling value | Supported estimate for each item or group | Mixed goods have usable market evidence | Estimates require condition-sensitive research |
| Relative net recovery | Estimated receipts less defined recovery costs | Repair or completion needs vary materially | Sensitive to uncertain expenses and outcomes |
| Category-first allocation | Supported group weights, then units within groups | A large load contains coherent subgroups | Weak group weights can hide distortion |
| Relative reference-retail weighting | Manifest retail amounts | Only as a carefully justified proxy | Retail references may be stale or incomparable |
Equal cost per unit
Divide the cost pool by the verified unit count. This is transparent for substantially similar merchandise, but poor for a lot containing both small accessories and major appliances. Define a unit first: a carton, multipack, individual piece, and complete set are not interchangeable.
Relative estimated selling value
Assign each item a share of the pool equal to its supported estimated selling value divided by the total supported value. Use relevant completed sales where available, matching model, condition, completeness, channel, and date. Active asking prices are weaker evidence because they do not demonstrate a completed transaction.
An estimate is a weighting input, not a price commitment or a gain recorded on receipt. Flag thin evidence and exclude clearly mismatched comparisons.
Relative net recovery
A recovery-based model can account for materially different preparation requirements. For each item or group, estimate selling receipts and deduct consistently defined recovery costs, such as missing components or necessary repairs, for weighting purposes.
Do not confuse those deductions with expenses already incurred or automatically deduct them from recorded inventory cost. Negative or unsupported weights need review, not mechanical insertion into a formula. This method is especially judgment-sensitive for salvage.
Category-first allocation
Allocate the pool among coherent categories using supported relative weights, then distribute each category’s share among sufficiently similar units. Electronics might need model-level treatment while identical packaged accessories can share a per-unit cost.
Do not allocate equally per pallet merely because each pallet occupies one handling position. Physical footprint rarely demonstrates equivalent economic content.
Reference-retail weighting
A manifest’s retail column may be retained as source data, but it does not establish resale value. Original prices can refer to different periods, pack sizes, configurations, or conditions. If reference-retail weighting is used as a provisional proxy, document why it is reasonable, its weaknesses, and the plan for review; avoid it when those differences make the results misleading.
A worked mixed-lot allocation example
Suppose a hypothetical received lot costs $2,400, with shipping already included. Inspection identifies three groups. Market research supplies illustrative selling-value weights; these figures are not PalletCove prices or promised outcomes.
| Group | Verified units | Assumed selling-value weight per unit | Extended weight | Allocated cost | Cost per unit |
|---|---|---|---|---|---|
| --- | ---: | ---: | ---: | ---: | ---: |
| Small appliances | 20 | $60 | $1,200 | $1,200 | $60 |
| Apparel | 40 | $20 | $800 | $800 | $20 |
| Accessories | 40 | $10 | $400 | $400 | $10 |
| Total | 100 | — | $2,400 | $2,400 | — |
The formula is:
Group allocation = total cost pool × group extended weight ÷ all groups’ extended weights.
The appliances receive $2,400 × $1,200 ÷ $2,400 = $1,200. Equal-unit allocation would instead assign $24 to every piece, shifting substantial cost from appliances into accessories.
The example deliberately makes the total illustrative weights equal the purchase cost. In real purchases, those totals need not match: the ratio, not the dollar coincidence, drives allocation. Allocated cost does not predict margin, and selling expenses remain separate considerations.
If additional costs qualify for capitalization, allocate them using an appropriate documented driver. A handling activity might follow cartons or processing time rather than estimated selling value. Every component must reconcile to an actual cost record, without duplicating shipping already included in the purchase price.
Build a worksheet that survives reconciliation
Keep both the original manifest and a working receiving file. Never overwrite source quantities or grades simply to make the spreadsheet agree with expectations.
- Identify the lot. Record invoice number, order date, total purchase cost, and payment reference.
- Preserve source details. Retain manifest identifiers, descriptions, quantities, grade definitions, and reference retail amounts.
- Count and classify receipts. Separate expected quantity from verified quantity and record shortages, unidentified items, and incomplete sets.
- Document evidence. Save comparable sales, inspection notes, research dates, and reasons for excluding weak comparisons.
- Apply the method. Calculate weights and allocations with visible formulas rather than unexplained manual amounts.
- Reconcile and approve. Ensure allocations equal the cost pool, resolve rounding differences, and retain dated revisions.
Include fields for allocated unit cost, actual sale proceeds, disposition, and any later accounting adjustment. A documented rounding rule prevents pennies from leaving the ledger out of balance.
If a piece becomes unsellable, do not silently delete it or move its cost onto the remaining units to conceal the loss. Record its disposition and determine the appropriate adjustment with your accountant. Distinguish errors discovered during initial receiving from later damage or impairment.
Ordering, payment, and delivery planning
Use the liquidation pallets hub to begin comparing formats. Buyers researching liquidation pallets in Texas or liquidation pallets in Florida receive the same free-shipping-only delivery option available throughout the 48 contiguous states.
Before ordering, review the listing, available manifest, quantity basis, condition description, and receiving requirements. Request clarification on ambiguous pack counts or grade terminology before committing. Category-level inventory may support only provisional group-level allocation until inspection.
Payment methods are credit/debit card, ACH bank transfer, and domestic bank wire. Handling takes 1–3 business days after payment clears; transit is typically 3–7 business days from Dallas. These are handling and typical transit windows, not a guaranteed arrival date; review the shipping policy for governing details.
Confirm that your location can receive the stated shipment format and organize safe unloading and inspection. Keep any resale certificate and business documentation requested for your order; PalletCove covers sales tax on qualifying orders, but that does not remove your separate resale-compliance responsibilities.
Financing decisions belong in a cash-flow analysis, not an inflated inventory valuation. The guide to liquidation inventory financing costs provides related planning context.
Delivery-day inspection, claims, and common mistakes
Photograph the shipment before disturbing wrapping, labels, or visible damage. Compare received handling units with delivery paperwork, note observable discrepancies on the delivery record, and retain a copy. Then reconcile item counts and condition findings as safely and promptly as practical.
Preserve packaging and identifying information relevant to a possible discrepancy. Follow the returns and claims policy for eligibility, procedures, required documentation, and applicable deadlines. As-is merchandise does not carry an assumed right to return individual items because they do not meet your resale expectations; do not presume that submitting a claim guarantees approval.
Keep a disputed quantity or condition finding visible in the worksheet. A potential supplier credit is not cash received, and its accounting treatment should follow your policy and supporting evidence.
Common mistakes include:
- Allocating by manifest count without verifying cartons versus pieces.
- Treating untested merchandise as tested working inventory.
- Using original retail prices as certain future sale receipts.
- Adding shipping again when freight is already included.
- Changing allocation methods between lots solely to influence reported margin.
- Confusing a cash-flow budget, an allocation worksheet, and a tax inventory calculation.
Frequently asked questions
Is liquidation inventory cost allocation the same as pricing?
No. Allocation assigns historical acquisition cost, while pricing considers condition, demand, competition, and selling costs. A seller may choose a price above or below allocated cost without changing the original allocation automatically.
Can I divide the purchase price by the manifest quantity?
That can be reasonable for sufficiently similar units after reconciling quantities. For unlike goods, equal-unit allocation can materially distort item costs, so document why the approach fits the lot.
What if there is no itemized manifest?
Create a receiving inventory with internal identifiers, counts, and inspection findings. Use a clearly labeled provisional allocation when necessary, then finalize it under a consistent policy once reliable information is available.
Should salvage receive a zero allocation?
Not automatically: salvage may have supportable parts or recovery potential, or it may have none. Document the evidence and distinguish initial allocation from subsequent write-downs or disposal accounting.
Does free shipping mean there is no inbound cost to allocate?
Shipping is already included in PalletCove’s listed price, so there is no separate shipping amount to add. Allocate the documented acquisition total and evaluate any separately incurred qualifying preparation costs without double counting.
Talk to PalletCove Liquidation
Ask about listing details, available manifests, shipment format, and order documentation before selecting a load. You can contact our order desk or review current inventory.
- Business: PalletCove Liquidation LLC
- Address: 4820 Cove Industrial Blvd, Dallas, TX 75236
- Phone: (713) 819-3904
- Email: sales@palletcoveliquidation.com
- Hours: Mon–Fri 8:00 AM – 6:00 PM CT, Sat 9:00 AM – 2:00 PM CT, Sun closed